

Debt Payoff Planner & Tracker
4.5

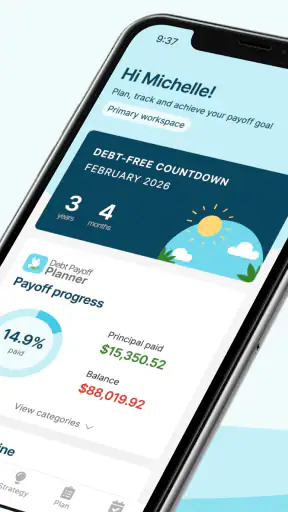
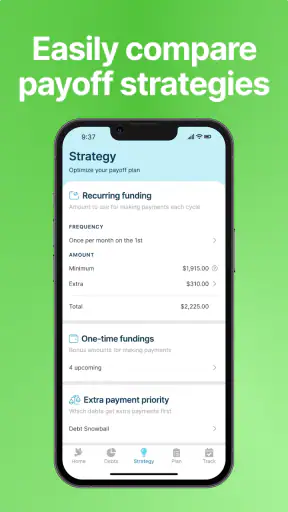
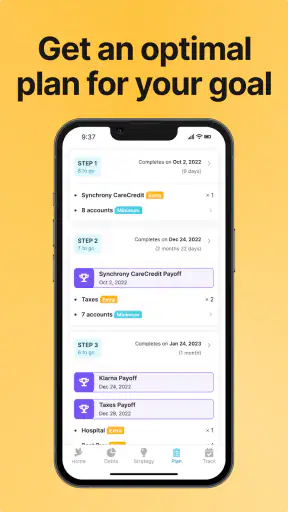
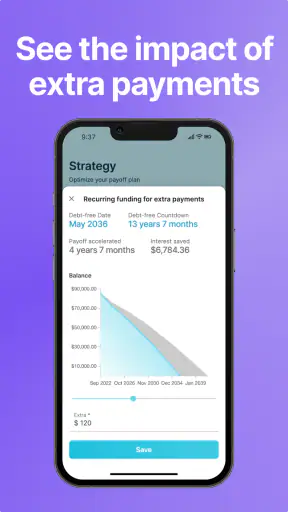
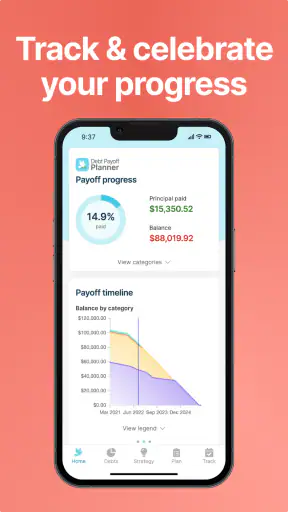
Paying down debt is rarely difficult because the arithmetic is complicated. The harder part is keeping the plan visible when everyday spending, changing bills, and a busy phone screen keep pulling attention elsewhere. Debt Payoff Planner & Tracker approaches that problem as a focused finance app: you enter the debts you want to tackle, choose a payoff direction, and use the plan as a regular reminder of what progress should look like. After spending time with it, I found the strongest part is not flashy automation but the way it turns an intimidating balance into a sequence of smaller decisions.
Debt Payoff Planner & Tracker is free to install, with optional in-app purchases ranging from $6.99 to $41.99 per item. It is made by Easily get a plan and stick to it - OxbowSoft LLC, carries an Everyone age rating, and belongs firmly in the personal finance category rather than banking or payment management. That distinction matters: I see it as a planning and motivation tool, not a replacement for your lender’s account, a budgeting bank connection, or professional debt advice.
How the planner feels when the connection is not perfect
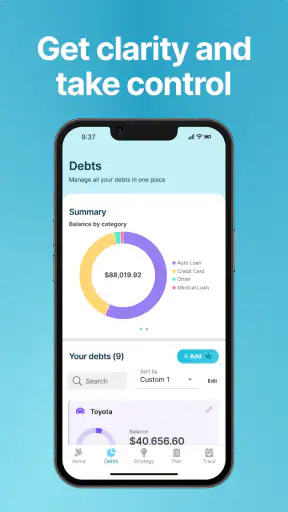
The app’s central experience is easy to understand on a phone. You work with debt information, a payoff target, and progress rather than wandering through a broad financial dashboard. That narrow purpose is useful because it keeps the emotional question in view: what should I pay next, and how will that choice change the route ahead?
Connectivity shapes the experience mainly around the moments when you expect a finance app to refresh or confirm something. A planner can show the figures you have entered, but it should not be confused with a live view of your credit-card or loan accounts. I would still open the lender’s own app or website before entering a new balance, interest detail, or minimum payment. That extra check is important because a payoff plan is only as reliable as the information behind it.
This creates a practical two-step routine. I would use the lender’s service as the source for current account details, then use this planner to decide how those details fit into the larger payoff strategy. The separation is actually helpful for people who do not want a planning tool mixed with payment credentials or a full account aggregation system. At the same time, it means there is some manual responsibility: when a balance changes, the plan needs your attention rather than silently correcting itself.
That limitation becomes more noticeable when you are moving between weak mobile service, a crowded commute, or a place where you cannot comfortably check several financial accounts. I would avoid treating a quick glance at the planner as proof that every balance is current. Instead, make updates during a deliberate review session, when you can compare statements and lender information without rushing. The app works best as a structured checkpoint, not as a live financial feed.
Useful mobile moments instead of constant checking
A phone is a good place for debt motivation because it is usually nearby when financial decisions happen. You may be considering a purchase, receiving a paycheck notification, or trying to decide whether an unexpected amount should go toward a card. A focused payoff view can make that decision more concrete than a spreadsheet hidden on a computer.
One realistic scenario is a monthly payday review. I would first check the latest balances with each lender, then open the planner and update the figures that have changed. From there, I could look at the planned order and decide whether the extra money is enough to follow the existing route or whether the month needs a more conservative adjustment. The useful habit is not tapping through the app every day; it is connecting a recurring money moment with a clear review of the plan.
Another good use is a short check before discretionary spending. If I am tempted to use a refund or bonus on something optional, seeing the remaining debt path can add context without requiring a complete household budget session. This is where the app’s motivational angle has practical value. It turns an abstract promise to “pay more” into a visible reason to pause.
I would not use it as the only tool for a complicated family budget, bill calendar, or shared spending system. A debt plan does not tell you whether the rent, utilities, food, insurance, and emergency savings are adequately covered. If directing every spare dollar to debt would leave you exposed to the next unexpected expense, a broader budgeting method may be the better first step. The planner is strongest after you have established a safe amount to allocate.
Choosing a payoff approach with more care
The most important decision is not simply entering the largest balance. Different payoff approaches can serve different personalities and financial situations. A method that creates an early sense of completion may help someone who needs visible wins, while a method focused on costly interest may make more mathematical sense for someone determined to reduce borrowing expense. The app is valuable when it helps you compare a route with your real motivation rather than blindly following a popular rule.
My practical advice is to run the plan with honest extra-payment figures. Do not build a schedule around a perfect month if your income varies. Use an amount you can maintain after essential bills and a modest buffer, then treat occasional extra money as a separate decision. A smaller payment that survives a difficult month is more useful than an ambitious target that forces you back onto a card.
A less obvious benefit of a dedicated planner is that it can expose the trade-off between speed and flexibility. Paying one debt aggressively may shorten that route, but it can also reduce the cash available for repairs or irregular bills. I would review the plan whenever income changes, not just when a debt is cleared. The right plan is not necessarily the fastest plan on paper; it is the one you can follow without creating another borrowing cycle.
There is also a psychological trade-off. A plan can make progress feel rewarding, but it can make a setback feel unusually visible. If interest, fees, or a new charge causes the balance to rise, the screen may feel discouraging even when you are still moving in the right direction. I found it more useful to judge progress over several review periods rather than reacting to one disappointing update.
What happens when information changes or the network gets in the way
Financial apps deserve a cautious recovery routine. If a page does not load, a calculation seems delayed, or you are unsure whether an update was saved, I would not immediately enter the same change repeatedly. First check whether the balance or plan visibly changed, then compare it with the lender’s current information before continuing. Duplicate entries or hurried corrections can create more confusion than a short delay.
When connectivity is unreliable, prepare before leaving a dependable connection. I would note the current balances and the amount I intend to review, then make changes later when I can verify the result. I would not assume that a screen viewed during a connection problem represents current lender information, and I would not make a payment simply because a planner displays a target. Payments still belong with the creditor or payment service that actually processes them.
This separation between planning and paying is one of the app’s clearest boundaries. The planner can help answer “how should I organize this?” but it does not replace the final confirmation that a payment was accepted, a minimum was met, or a transaction posted. For anyone who wants one app to import accounts, monitor transactions, and execute payments, a connected banking or debt-management service may feel more convenient. That convenience can also involve more setup and a larger amount of financial information in one place, so the better choice depends on your comfort and priorities.
Recovery is also about recovering from life, not just from a technical interruption. If you miss a planned payment amount because of an urgent expense, do not abandon the entire plan. Update the figures honestly, lower the next target if necessary, and continue from the new starting point. A debt tool becomes harmful when it encourages shame instead of adjustment. I prefer using it as a neutral record that helps me restart quickly.
Keeping mobile data and financial attention under control
Because this is a focused planner rather than a complete financial command center, I would use it in short, intentional sessions. There is little benefit in repeatedly opening it throughout the day if your balances have not changed. A scheduled review reduces unnecessary checking and makes it easier to distinguish a real financial update from anxiety-driven refreshing.
For a data-conscious routine, gather information from lender statements or official account views first, then update the planner in one sitting. Avoid entering guesses just to make the screen look current. A guessed minimum payment or rounded balance can make a payoff schedule appear more reassuring while quietly weakening its usefulness. Accuracy matters more than having every field filled immediately.
I would also be selective about where I use the app. A personal phone with a screen lock is a more sensible setting than a shared device, especially when debt names and balances are visible. I would avoid discussing or entering financial details while someone is looking over my shoulder, and I would not treat a finance app as a secure vault for documents or account credentials. The app’s value comes from organized planning, not from storing every piece of financial life in one place.
One advanced workflow is to separate the “known” amount from the “possible” amount in your own review notes. The known amount is what you can safely commit after essentials and a buffer. The possible amount includes overtime, gifts, refunds, or spending reductions that may not repeat. I would build the regular plan around the first figure and use the second only when it is actually available. This prevents an optimistic month from becoming a permanent obligation.
Another useful habit is to record why a plan changed. If the payment target drops because of an annual bill, medical cost, or income shift, that context helps prevent a later overreaction. Without context, you may look at the lower payment and assume you failed. With context, you can see that the plan adapted as it should. This is a small discipline, but it makes a tracker more useful over time.
Who will benefit most, and who should choose something else
I think this app suits someone with several debts who wants a clear payoff route without adopting a full budgeting platform. It is also a good fit for a person who responds to visible milestones and needs a regular prompt to stay engaged. Someone beginning their first serious payoff effort may appreciate the narrower scope because it avoids the distraction of investment tools, spending categories, and unrelated financial features.
It is less suitable for a person who expects automatic, constantly synchronized account balances. It may also feel limited if your main problem is controlling everyday spending rather than deciding how to prioritize existing debt. In that case, a budgeting app with transaction categorization may offer more immediate help. If you need advice about insolvency, repayment negotiations, or legal obligations, a qualified counselor is more appropriate than any tracker.
Compared with a spreadsheet, the app is easier to consult on a phone and more naturally tied to motivation, while a spreadsheet offers greater freedom for custom formulas and household scenarios. Compared with a lender’s own app, it provides a broader view across debts, but it is not the authoritative place for payment status. Compared with a full financial dashboard, it is simpler and less sprawling, though that simplicity means you will handle more updates yourself.
Its established presence is reassuring without being a reason to stop checking the numbers: the app holds a 4.5 average from around 4.7 thousand ratings, has about 1.2 thousand written reviews, and has passed 500 thousand installs. It was released in January 2015, and version 2.54 supports Android 6.0 and later. Those details make it accessible to many older Android devices, although anyone using an older phone should still expect the experience to depend on the device and its connection.
My verdict on staying connected to the plan
After using it as a planning companion, I see Debt Payoff Planner & Tracker as most effective when you give it a defined job: organize debt priorities, make progress visible, and support a repeatable review habit. It does not remove the need to verify balances, protect your financial information, or make payments through the proper creditor channel. That is not a weakness by itself, but it is a boundary every new user should understand.
The connectivity angle reinforces that conclusion. I would use a reliable connection for the initial setup and for updates that depend on current lender information, then avoid treating the app as a live account monitor when service is uncertain. A short, planned session is better than constant refreshing. If the network fails, pause, verify what changed, and resume when you can check the figures calmly.
For me, the best reason to try it is the combination of focus and accountability. It gives debt a place on the phone without turning the phone into a noisy financial dashboard. The main compromise is manual care: you must bring accurate information into the plan and keep your expectations realistic. If that sounds manageable, the free starting point makes it an easy tool to test. If you need automatic synchronization, payment execution, or complete household budgeting, I would choose a more specialized alternative instead.
Overall, I would recommend it to a friend who already knows what they owe and wants help deciding how to keep moving. Use it beside official lender accounts, review it at a consistent time, protect your screen and information, and let the plan adapt when real life interrupts. Used that way, Debt Payoff Planner & Tracker is not a magic shortcut out of debt, but it is a practical mobile reminder that turns a vague goal into a routine you can actually follow.
4.5
1.23K Reviews
Pros
- Creates clear payoff plans using the debt snowball or avalanche methods.
- Tracks balances
- interest rates
- minimum payments
- and payoff progress.
- Supports multiple debts in one organized dashboard.
- Shows estimated payoff dates and potential interest savings.
- Helpful reminders can encourage consistent payment habits.
Cons
- Advanced planning tools may require a paid subscription.
- Results depend on entering accurate and up-to-date debt details.
- No direct bill payment or automatic debt-account syncing.
- The interface may feel complex for users with only one debt.
- Interest and payoff estimates may differ from your lender’s figures.


